Taxation of Foreign Pensions in Italy: What You Need to Know
Retiring in Italy is a dream until you realize the local tax agency wants nearly half of your hard-earned foreign pension. I almost booked a flight back home when my accountant showed me my first Italian tax projection under standard rates. This guide explains exactly how Italy taxes your foreign pension and how you can legally shield it.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
The Brutal Reality of Italian Tax Residency
How the 183 Day Rule Traps Your Pension
The biggest shock for retired expats is discovering that Italy does not just tax the money you make within its borders; it taxes your global wealth. If you spend more than 183 days a year in Italy, you are legally classified as an Italian tax resident.
In Italy, foreign pensions are usually taxable as worldwide income for residents. Tax treaties may assign taxation rights or allow credits for foreign taxes paid. Public pensions are often taxed in the paying country, while private pensions are typically taxed in Italy. Reporting and compliance obligations are essential for avoiding penalties.
The moment you hit that 184th day, the Agenzia delle Entrate (Italian Revenue Agency) applies the principle of worldwide taxation. This means your US Social Security, your UK State Pension, your private corporate pensions, and your 401(k) distributions are all suddenly subject to Italy’s progressive income tax, known as IRPEF.
Because IRPEF is a progressive tax, the rates scale up aggressively. If your combined pension income is substantial, you will rapidly find yourself in the highest brackets, surrendering up to 43% of your retirement income to the Italian state. If you are trying to calculate your monthly survival budget, looking closely at the Italian Income Tax Brackets for 2026 is a necessary, albeit painful, reality check.
Understanding Bilateral Tax Treaties
A common and highly dangerous assumption among expats is the belief that because they already paid taxes on their pension in their home country, they will not have to pay taxes in Italy.
While Italy has Double Taxation Treaties with countries like the US, the UK, and Canada, these treaties do not magically lower your tax rate. Instead, they prevent you from being taxed twice on the exact same euro. Under most treaties, Italy has the primary right to tax your private and state pensions once you reside there. You will receive a foreign tax credit for whatever you paid to your home country, but if Italy’s tax rate is higher (which it almost always is), you must pay the difference to the Italian government.
There is one major exception: government pensions. If your pension stems from civil service, military service, or specific public sector work, bilateral treaties generally dictate that this pension is taxable only by the country that pays it. Navigating the nuances of these treaties, especially when trying to claim foreign tax credits, is a massive administrative headache that we explore deeply in our guide on US-Italy Tax Compliance Form 8891 vs Modello 730.
The Seven Percent Flat Tax Lifeline for Retirees
Qualifying for the Southern Italy Pensioner Regime
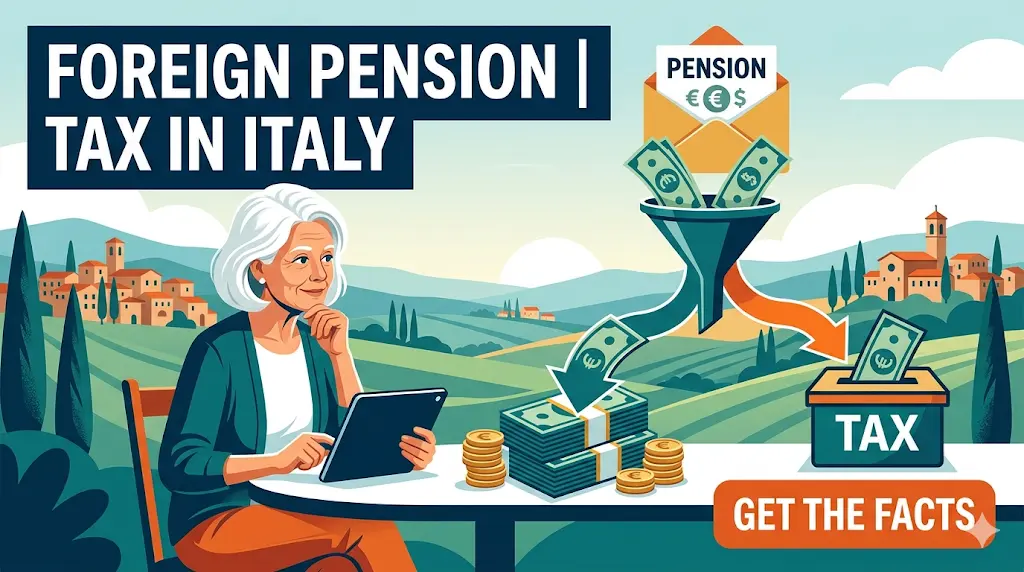
If paying 43% on your pension makes you reconsider your move, the Italian government offers a massive legal loophole explicitly designed to attract foreign retirees. To combat economic stagnation and depopulation in specific regions, Italy created a flat 7% tax regime for pensioners.
If you move to an eligible municipality in Southern Italy (which includes regions like Sicily, Puglia, Abruzzo, Sardinia, Campania, Basilicata, Molise, and Calabria) with a population of under 30,000 residents, your entire foreign pension is taxed at a flat 7%. This incredibly low rate applies to all of your foreign-sourced income, including overseas rental yields and foreign dividends, and it lasts for an astonishing 10 years.
To qualify, you must currently receive a foreign pension and you must not have been an Italian tax resident for the past five consecutive years. If you are looking to retire and draw down heavy retirement accounts, this regime fundamentally alters the mathematics of your relocation. For a specific breakdown on how this applies to American retirement structures, review Tax on 401(k) and IRA if Moving to Italy.
Wealth Tax Exemptions and Quadro RW Relief
Beyond slashing your income tax, the 7% pensioner regime offers an equally massive bureaucratic superpower: it completely exempts you from Italy’s wealth taxes and foreign asset reporting laws.
Under standard Italian tax law, residents must declare every single foreign bank account, investment portfolio, and overseas property they own on a highly invasive tax form known as the Quadro RW. This declaration triggers the IVIE wealth tax on foreign real estate and the IVAFE wealth tax on foreign financial assets. It is a grueling, expensive process for your accountant to manage every year.
If you opt into the 7% regime, you are entirely exempt from filing the Quadro RW, and you pay zero IVIE or IVAFE taxes on your global assets.
| Tax Feature | Standard IRPEF Residency | 7% Foreign Pensioner Regime |
| Tax Rate on Pension | Progressive (23% up to 43%) | Flat 7% |
| Tax on Foreign Dividends | 26% Flat Rate | Flat 7% |
| Quadro RW Reporting | Mandatory every year | Exempt |
| IVAFE (Wealth Tax on Assets) | 0.2% Annually | Exempt |
| Required Location | Anywhere in Italy | Southern Italy (Towns < 30,000 pop.) |
For standard expats not lucky enough to qualify for this regime, learning how to stay compliant with these asset monitoring laws is mandatory. You can read exactly what is required in Declaring a Foreign Property in Italy’s Quadro RW.
Moving and Managing Your Pension Funds
Defeating Predatory Exchange Rates
Regardless of which tax regime you fall into, you still face the logistical nightmare of physically moving your pension money into Italy to pay for your daily life. If your pension is disbursed in US dollars, British pounds, or Australian dollars, sending a direct international SWIFT wire from your home bank to a traditional Italian retail bank is a terrible financial move.
Traditional banks will hit you with an outgoing wire fee, an intermediary fee, and, most destructively, a hidden 3% to 5% markup on the exchange rate. To stop this bleeding, veteran expats route their monthly pension distributions through Wise. By having your home country pension deposited into your Wise account, you can convert your funds to euros exactly at the mid-market exchange rate, avoiding institutional markups entirely.
Wise also provides you with a localized European IBAN. Once your pension is converted to euros inside Wise, you can pay your Italian landlord, your utility bills, and your local taxes directly without friction. Keeping your daily operational cash flow running through Wise ensures you retain your purchasing power, helping you accurately manage your Cost of Living in Italy 2026 Budgeting for Expats. It is also the smartest way to ensure you have local euros on hand, which is vital when reviewing Avoiding ATM Withdrawal Fees in Italy.
Safeguarding Your Nest Egg from Local Inefficiencies
While you use a modern financial platform for your daily cash flow, you must be incredibly careful with where you park the bulk of your retirement savings. Transferring your entire life savings or investment portfolio into a traditional Italian retail bank exposes your wealth to exorbitant account maintenance fees and heavily taxed, underperforming local mutual funds.
Smart expats keep their primary global wealth centralized in Interactive Brokers. Keeping your major retirement capital securely parked in a globally regulated platform like Interactive Brokers allows you to continue investing in international equities with microscopically low commission fees, completely insulated from the notoriously slow Italian banking sector.
When you need a larger lump sum—perhaps to buy a car or put a down payment on a Tuscan villa—you simply liquidate a small portion of your assets inside Interactive Brokers. You then transfer those specific funds to your digital multi-currency wallet to handle the exchange rate, and deploy the euros locally. Furthermore, Interactive Brokers provides clean, standardized annual tax reports that make calculating your Italian tax liabilities significantly easier for your commercialista. Securing these tools before you begin tangling with local town halls, as detailed in Navigating Italian Bureaucracy Comune and Prefettura, ensures your finances remain protected even if your physical paperwork is delayed. Ensure you have properly completed Checking Your Italian Tax Code (Codice Fiscale) Status so you can legally link these powerful international financial accounts to your Italian identity.
References
Primary sources (official)
- Agenzia delle Entrate – Agevolazioni per i pensionati esteri – https://www.agenziaentrate.gov.it/portale/schede/agevolazioni/regime-opzionale-per-i-pensionati-esteri-che-cose-cittadini
- Ministero dell’Economia e delle Finanze – Convenzioni per evitare le doppie imposizioni – https://www.finanze.gov.it/it/Fiscalita-dellUnione-europea-e-internazionale/convenzioni-e-accordi/convenzioni-per-evitare-le-doppie-imposizioni/
Other helpful sources
- IRS (US Department of the Treasury) – United States-Italy Income Tax Treaty – https://www.irs.gov/businesses/international-businesses/italy-tax-treaty-documents
- Your Overseas Home – 7% tax scheme extended to larger Italian towns – https://www.youroverseashome.com/italy/articles/7-tax-scheme-extended-to-larger-italian-towns/
Disclaimer
The information provided in this article is for educational and informational purposes only and does not constitute official tax, financial, or legal advice. Italian tax laws, progressive IRPEF brackets, double taxation treaties, and the specific municipal population requirements for the 7% flat tax regime are highly complex and subject to frequent legislative updates. Always consult directly with a dually qualified international tax advisor or a certified Italian commercialista to review your specific pension structures, evaluate your eligibility for tax regimes, and file your annual tax returns.