How to Switch Banks in Italy Without Disrupting Direct Debits
Getting your first Italian bank account feels like a massive victory, but realizing three months later that the monthly fees are eating your gelato budget is a soul-crushing experience. I once spent four hours in a drafty branch in Trastevere just trying to figure out why my internet bill was rejected by my own bank despite having plenty of funds. This guide will walk you through the precise, legally protected steps to switch Italian banks without losing your sanity or your electricity.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
Understanding the Italian Portability Law
For years, moving your money from one Italian institution to another was a nightmare of paperwork and "missing" signatures. However, thanks to the Legge sulla Portabilità (Portability Law), which follows EU directives, the process has become significantly more structured. This law was designed specifically to prevent banks from holding customers hostage with overly complex exit requirements and hidden closing costs.
The 12 Day Rule and Your Rights
Under current Italian regulations, the process of switching your bank account—including the transfer of all active direct debits (SDD or Sepa Direct Debits)—must be completed within 12 business days. This is a hard deadline. If the banks involved fail to meet this timeline, you are technically entitled to compensation for each day of delay. I have seen expats successfully claim these small penalties, though the real "win" is simply having your bills paid on time.
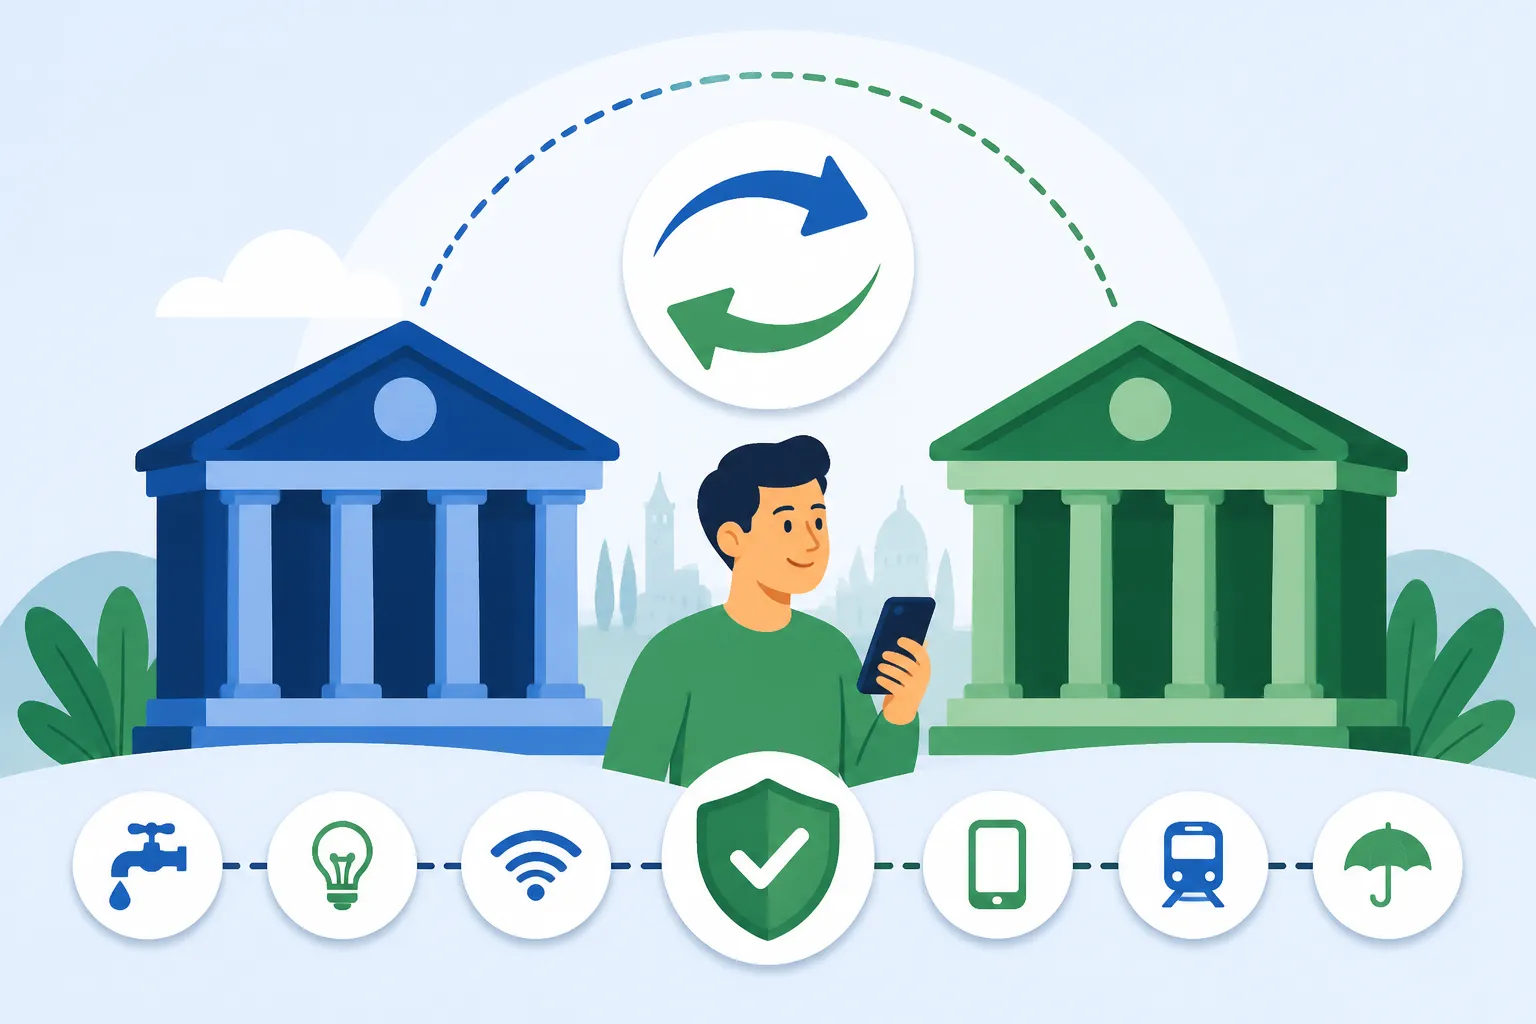
When you initiate the switch, your new bank acts as the primary point of contact. You shouldn't have to spend your mornings arguing with the teller at your old branch. The new bank provides a standardized form where you authorize them to "pull" your balance, your recurring payments, and even your standing orders for rent from the old institution. This centralized approach is meant to minimize the friction that often characterizes Navigating Italian Bureaucracy: Comune and Prefettura.
The Role of the New Bank as Your Liaison
Choosing the right partner for your new financial life is the first hurdle. Many foreigners find that digital-first options or international-friendly banks offer better interfaces than the traditional, dusty local banks. During this transition, using a service like Wise can be incredibly helpful for maintaining liquidity in Euros while your main accounts are in flux. Wise allows you to hold a balance and pay bills via IBAN, providing a safety net if your primary Italian account experiences a momentary hiccup during the 12-day transfer window.
Your new bank will handle the heavy lifting of communicating with the old one. You will fill out a document called the "Modulo di richiesta di trasferimento dei servizi di pagamento." In this form, you can choose whether to close the old account entirely or just transfer specific services. For most of us, closing the old account is the goal to avoid those pesky "spese di gestione" that seem to never end.
Preparing for the Move Without the Drama
Before you sign that transfer request, you need to do a bit of digital housekeeping. Italian utility companies—Enel for electricity, Eni for gas, and TIM or Vodafone for internet—can be notoriously unforgiving if a payment bounce occurs. They don't just send a polite email; they might restrict your service or add "mora" (late fees) to your next three bills.
Auditing Your Active Direct Debits
Log into your current banking app and look for the section labeled "Mandati SDD" or "Domiciliazioni." List every single one out. In Italy, your bank account isn't just for money; it’s the anchor for your Cost of Living in Italy 2026: Budgeting for Expats. You likely have direct debits for your Tari (trash tax), your Bollo Auto (car tax), and perhaps your gym membership.
It is vital to check if any of these payments are due within the 12-day transition window. If a bill is due on day 5 of your switch, the old bank might have already processed it, or the new bank might not yet have the mandate active. My personal rule of thumb? Always keep enough cash in the old account to cover one final month of the largest bill, just in case the "handover" misses a beat.
The Importance of the Codice Fiscale and SPID
Everything in Italy is tied to your tax code. When you open the new account, ensure they have your How to Get a Codice Fiscale in Italy (and Why You Need One) recorded correctly. Even a single character error can cause the automated "switch" system to fail because the two banks cannot verify that the account holder is the same person.
Furthermore, ensure your SPID and Digital Identity for Italian Tax and Services is active and linked to your phone. Many modern Italian banks require SPID for high-level authentication when setting up new payment mandates. If you are switching to a bank like Intesa Sanpaolo or Fineco, having your digital ID ready will make the "identity check" phase of the switch take minutes instead of days.
The Step-by-Step Switching Process
Once you’ve audited your bills and selected a new bank, it’s time to pull the trigger. Do not try to manually cancel and recreate direct debits yourself. This is the most common mistake expats make. If you cancel a mandate with the utility company directly, they might revert you to "bollettino postale" (paper bills paid at the post office), which is a massive step backward in efficiency.
Filling Out the Transfer Request
You will visit your new bank (or use their app) and request the "trasferimento del conto." You will need the IBAN of your old account and a list of the services you want to migrate. You have three choices:
- Transfer everything and close the old account.
- Transfer only the direct debits but keep the old account open.
- Transfer only the remaining balance.
I highly recommend option one. Keeping an old Italian account open "just in case" usually leads to you being charged an annual stamp duty (Imposta di Bollo) of 34.20 Euro if your balance exceeds 5,000 Euro, plus monthly maintenance fees. If you are worried about tax implications of closing accounts, consulting Taxes for Expats can help you understand how to report these changes on your annual filings, especially if you are also managing assets outside of Italy.
The Observation Period
Once the request is submitted, the new bank sends a "test" to the old bank. This is where the 12-day clock begins. During this time, do not change any settings in either portal. You will see your balance move first, followed by the appearance of your "Domiciliazioni" in the new app. If you see a direct debit for your electricity disappear from the old bank but not yet show up in the new one after 10 days, call the new bank's customer service immediately and mention the "12-day portability limit." They usually move much faster when they know you’re aware of the law.
Handling International Transfers During the Switch
If you receive your salary from abroad or have recurring transfers from a US or UK account, you need to update those senders manually. The Italian portability law only covers SEPA direct debits within the European system. It does not automatically notify your employer in London or your pension provider in New York. This is where Wise remains the hero of the story; you can redirect your foreign income to your Wise IBAN temporarily while you wait for the new Italian account to be fully verified and ready for large incoming transfers.
Managing Specific Italian Utilities and Subscriptions
Every utility provider in Italy handles bank switches slightly differently. While the law says it should be seamless, the reality on the ground often requires a quick "check-in" to ensure your lights stay on.
Electricity and Gas (Enel, Eni, Iberdrola)
These companies are usually the most "automated" when it comes to the SEPA system. However, they are also the most prone to errors. After your switch is complete, wait about a week and then log into your utility provider's online portal (like the MyEnel app). Check the "Metodo di Pagamento" section. It should now show your new IBAN. If it still shows the old one, or says "da definire" (to be defined), manually update it there using your new details. This extra five minutes of work can prevent a "servizio sospeso" notice.
Internet and Mobile (TIM, WindTre, Fastweb)
Telecom companies in Italy are notorious for their billing complexities. Sometimes, they link a "promotion" to a specific bank account or credit card. When you switch, that link might break. If you notice your internet bill is suddenly higher, it’s likely that the "direct debit discount" was removed during the transition. A quick call to their "servizio clienti" will usually fix this, but you have to be the one to catch it.
| Service Type | Typical Transfer Ease | Veteran Tip |
|---|---|---|
| Electricity/Gas | High | Check the provider app 5 days after the switch. |
| Home Internet | Medium | Ensure no "hidden" modem installments are blocked. |
| Gym Memberships | Low | Often requires a manual update at the front desk. |
| Car Insurance | Medium | Make sure the "scadenza" doesn't hit during the 12 days. |
| Local Taxes (Tari) | Low | Often requires a visit to the local Comune website. |
The "Bollo Auto" and Annual Taxes
If you have set up your car tax (Bollo Auto) to be paid automatically via your bank (common in regions like Lombardia for a 15% discount), be extremely careful. These are often processed by regional agencies, not the bank itself. You may need to log into the ACI (Automobile Club d'Italia) website with your SPID and Digital Identity for Italian Tax and Services to confirm the new IBAN is registered for the upcoming year's payment.
Post-Switch Maintenance and Tax Compliance
Once the dust settles and your new debit card arrives in the mail (always a celebration!), there are a few administrative loose ends to tie up. Switching banks isn't just about moving money; it's about updating your financial identity in Italy.
Notifying Your Accountant (Commercialista)
If you are a freelancer or a high-net-worth individual, your bank switch needs to be documented. When the time comes for Filing Taxes in Italy: Modello 730 vs Redditi PF, your accountant will need the "Estratto Conto" (bank statement) from both the old bank (covering January until the closing date) and the new bank.
Don't forget to download every single statement from your old bank's portal before they shut off your access. Once that account is closed, getting a PDF of a statement from three months ago can cost you 10-20 Euro in "search fees" at a physical branch. For those with complex international holdings, Taxes for Expats can provide specialized advice on how this closure affects your FBAR or other home-country reporting requirements.
Monitoring for "Spese Impreviste"
In the first two months after a switch, keep a close eye on your new account for any "commissioni" you don't recognize. Sometimes, the new bank might charge a small fee for "importing" a mandate, although this is becoming rarer as they compete for customers. Knowing How to Reduce Bank Fees in Italy as a Foreigner will help you identify which charges are standard and which you should dispute. If your new bank starts nickel-and-diming you for every direct debit, it might be time to have a stern word with your "consulente" at the branch.
The Peace of Mind of a Successfull Transition
When you finally see that first Enel bill hit your new account without you having to lift a finger, you’ll know you’ve truly mastered the system. It takes patience and a bit of "I've-been-there" skepticism, but the 12-day portability law is one of the few bureaucratic tools in Italy that actually works in your favor.
If you are still looking for the perfect landing spot for your funds, checking out the Best Bank Accounts for Expats in Italy: Fees and Benefits can give you a head start on avoiding the high-fee traps of the past. And remember, while you are waiting for the banks to talk to each other, keep your How to Open a Bank Account in Italy: Requirements and Tips checklist handy to ensure you haven't missed any regional requirements that might differ between the North and South. Staying organized is the only way to beat the "sistema."
Disclaimer
The information provided in this guide is for educational and informational purposes only and does not constitute professional financial, legal, or tax advice. Banking regulations in Italy, including the 12-day portability law, are subject to change by the Banca d'Italia and European regulatory bodies. While we strive to provide the most current and hyper-local advice, individual experiences with specific bank branches or utility providers may vary based on regional policies and internal bank procedures. Always consult with a certified commercialista or financial advisor regarding your specific tax obligations and financial situation in Italy.