Italy’s Tax Treaties: Avoiding Double Taxation
Navigating international tax obligations is a primary concern for expatriates. This guide explores Italy’s extensive network of double taxation treaties, explaining how these agreements protect your income from being taxed twice and ensure a smoother financial transition to Italian life.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
Navigating the Complexities of International Taxation in Italy
Relocating to Italy is an adventure that offers a high quality of life, but it also introduces a complex web of fiscal responsibilities. For the international community, one of the most daunting aspects of moving abroad is the prospect of being taxed on the same income by two different countries. Without a clear strategy, a professional earning a salary or a retiree receiving a pension could find their disposable income severely depleted by competing tax authorities.
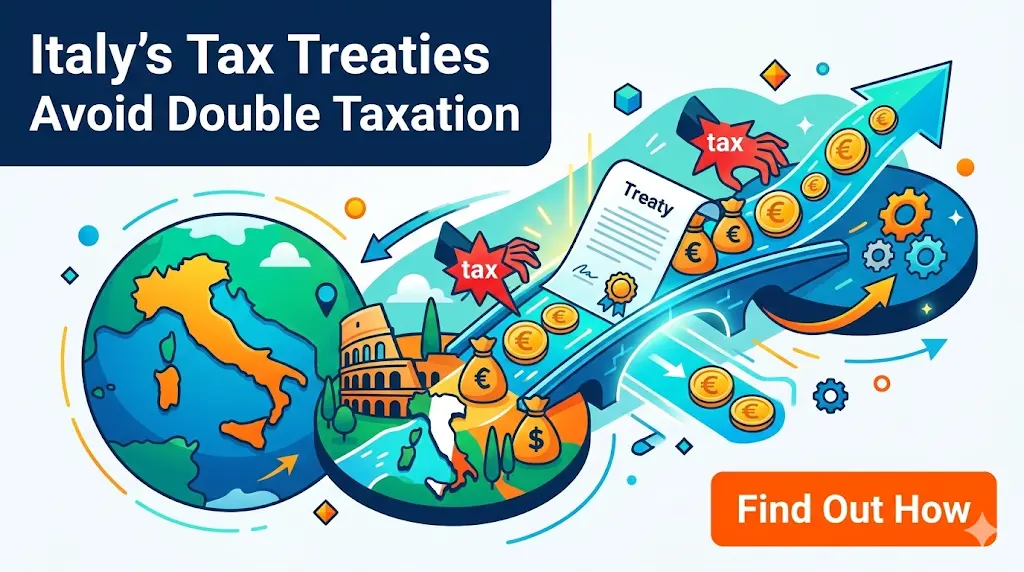
Italy, recognizing the importance of global mobility and foreign investment, has established a robust framework of bilateral agreements known as Double Taxation Treaties (DTTs). These treaties are designed to determine which country has the primary right to tax specific types of income, thereby preventing the same euro or dollar from being sliced twice. For anyone planning a long-term stay, understanding these rules is as essential as Understanding Italy’s Tax System: A Guide for Foreigners to ensure long-term financial health.
The Principle of Worldwide Taxation and Residency
To understand how tax treaties work, one must first grasp the concept of tax residency in Italy. The Italian Revenue Agency (Agenzia delle Entrate) follows the principle of worldwide taxation for its residents. If you are considered a tax resident in Italy, you are legally required to report and pay taxes on your global income, regardless of where in the world it was earned.
In Italy, you are generally considered a tax resident if, for more than 183 days in a calendar year, you are registered in the local population registry (Anagrafe), have your habitual abode in Italy, or have your main center of business and social interests within the country. This transition to residency often begins with Registering with Comune: Residency, School, Health Card to solidify your legal standing. Tax treaties step in when your home country also claims you as a resident or seeks to tax income generated within its borders, providing “tie-breaker” rules to settle the dispute.
How Double Taxation Treaties Protect Expatriates
A Double Taxation Treaty is a formal agreement between two nations that allocates taxing rights and provides mechanisms for tax relief. Italy has signed over 100 such treaties with countries including the United States, the United Kingdom, Canada, Australia, and most EU member states. These agreements serve several critical functions for the expat.
Preventing Overlap of Taxing Rights
Treaties categorize different types of income—such as dividends, interest, royalties, and employment income—and specify which country has the right to tax them. For example, employment income is usually taxed in the country where the work is physically performed.
Providing Mechanisms for Tax Credits
When both countries have a right to tax a specific income stream, the treaty ensures that the taxpayer is not penalized. Usually, the country of residence (Italy) will allow a foreign tax credit for the taxes already paid to the source country. This ensures that the total tax paid does not exceed the higher of the two countries’ rates.
Reducing Withholding Taxes
Treaties often reduce the “withholding tax” rates on passive income like dividends or interest. Without a treaty, a country might take 30% off the top of a dividend payment to a non-resident. Under a DTT, this rate is often slashed to 15%, 10%, or even 5%, allowing more of your investment returns to reach your Italian bank account.
Common Income Types Covered by Italian Treaties
Italian tax treaties are comprehensive, covering a wide array of financial activities. While each treaty is unique, most follow the OECD Model Tax Convention structure.
| Income Type | Typical Treaty Treatment |
| Employment Income | Taxed where the work is physically performed. |
| Dividends | Taxed in the country of residence, but source country can withhold a limited % (often 15%). |
| Interest | Usually taxed in the country of residence with a low source-country withholding (often 10%). |
| Real Estate Income | Taxed in the country where the property is located. |
| Pensions | Generally taxed only in the country of residence (with exceptions for government service). |
| Capital Gains | Usually taxed in the country of residence (except for real estate gains). |
Real Estate and Rental Income
A common area of confusion for expats is the treatment of rental income from a property held in their home country. Almost all of Italy’s treaties state that income from immovable property is taxed in the country where the property is situated. However, because Italy taxes its residents on worldwide income, you must still report this income on your Italian return. You then claim a credit for the taxes paid abroad.
Pensions and Social Security
For retirees, the treatment of pensions is paramount. Most treaties grant the exclusive right to tax private pensions to the country of residence. If you move to Italy and receive a private pension from the UK or USA, Italy will typically be the only country to tax it. However, government service pensions (e.g., for former civil servants or military) are often taxed only by the paying country.
The Tie-Breaker Rules: Who Claims You?
In some cases, an expat might be considered a tax resident by two countries simultaneously under their respective domestic laws—a situation known as “dual residency.” To resolve this, tax treaties include “tie-breaker” rules. These rules are applied in a specific hierarchical order:
- Permanent Home: Where does the individual have a permanent home available to them?
- Center of Vital Interests: Where are the individual’s personal and economic ties closer (family, work, social clubs)?
- Habitual Abode: Where does the individual spend more time?
- Nationality: Which country’s passport do they hold?
Special Incentives and Treaty Interactions
Italy has introduced several aggressive tax regimes to lure foreign residents, such as the Lavoratori Impatriati (Inpatriate Workers) scheme and the flat tax for High-Net-Worth Individuals. It is crucial to understand how these interact with tax treaties.
Inpatriate Workers and Treaties
The inpatriate regime offers a 50% or higher exemption on Italian-sourced income. If you are an expat from a country like the US, which taxes based on citizenship regardless of residence, the interaction between the Italian exemption and the US Foreign Tax Credit can be complex. You might find that the Italian tax break simply results in you paying more to the IRS, unless you properly utilize the treaty’s provisions for re-sourcing income.
The 7% Pensioner Tax
The popular 7% flat tax for retirees moving to Southern Italy is a domestic Italian law. However, to benefit from it, your pension must be “foreign-sourced.” The tax treaty determines what constitutes a foreign pension and whether your home country has relinquished its right to tax it.
Managing Wealth Taxes: IVIE and IVAFE
Italy doesn’t just tax income; it taxes wealth held abroad. These are known as IVIE (tax on foreign real estate) and IVAFE (tax on foreign financial assets).
The Role of DTTs in Wealth Taxation
While most tax treaties focus on income, some also cover taxes on capital (wealth). If a treaty covers wealth taxes, you may be able to credit taxes paid on property or assets in your home country against your IVIE or IVAFE liability in Italy.
- IVIE: Usually 1.06% of the property value.
- IVAFE: Usually 0.2% of the value of financial assets (like brokerage accounts).
Practical Steps to Claim Treaty Benefits
Claiming the benefits of a tax treaty is not automatic; it requires administrative action in both countries.
- Certificate of Tax Residence (CoR): To prove to your home country that you are a resident of Italy, you must obtain a Certificato di Residenza Fiscale from the Agenzia delle Entrate. This prevents your home country from withholding too much tax at the source.
- Tax Return Filings: On your Italian tax return (Modello Redditi), you must specifically claim the foreign tax credit for taxes paid abroad.
- W-8BEN or Equivalent: If you have US-sourced income, you must file a Form W-8BEN with your US financial institutions to notify them of your Italian residency and your eligibility for reduced treaty rates.
Avoiding Common Pitfalls
Even with treaties in place, expatriates often make mistakes that lead to fiscal headaches.
- Failure to Register with AIRE: For Italian citizens living abroad, or those with dual citizenship, failing to register with the Registry of Italians Residing Abroad (AIRE) can lead to the Italian government claiming you are still a resident and taxing your global income.
- Inconsistent Reporting: If you tell your home country you are a resident there to keep a specific bank account or benefit, but tell Italy you are a resident here, you risk an audit from both sides.
- Ignoring Local Surtaxes: Remember that treaties generally apply to national income taxes. Regional and municipal surtaxes in Italy are calculated based on the final IRPEF amount and are often not specifically covered by treaty credits in the same way.
Conclusion
Italy’s extensive network of tax treaties provides a vital safety net for expatriates, ensuring that the transition to an Italian lifestyle is not overshadowed by unfair taxation. By clearly defining residency, providing mechanisms for tax credits, and reducing withholding rates on passive income, these agreements allow you to manage your global wealth with confidence.
However, the benefits are not passive; they require active management, proper documentation, and an understanding of how Italian domestic incentives interact with international law. By leveraging these treaties, you can protect your hard-earned income and focus on what truly matters: embracing the culture and beauty of your new life in Italy.
References
Primary sources (official)
- Agenzia delle Entrate (Italian Revenue Agency): The official portal for tax treaty texts, residency requirements, and the “Quadro RW” reporting for foreign assets. https://www.agenziaentrate.gov.it/portale/web/english
- Ministero dell’Economia e delle Finanze (MEF): The Italian Ministry of Economy and Finance, providing the legal framework for international tax agreements. https://www.mef.gov.it/en/
Other helpful sources
- PwC Global Tax Summaries – Italy: A detailed professional guide to individual taxation, residency, and double tax relief in the Italian market. https://taxsummaries.pwc.com/italy/individual/foreign-tax-relief-and-tax-treaties
Disclaimer
The information provided in this article is for general informational and educational purposes only and does not constitute professional tax, legal, or financial advice. Tax treaties and domestic tax laws in Italy are subject to frequent changes and complex interpretations. Every individual’s tax situation is unique, and treaty benefits depend on the specific agreement between Italy and your home country. Always consult with a certified Italian accountant (commercialista) or a licensed international tax professional before making significant financial decisions or filing tax returns in multiple jurisdictions.