How to Avoid Double Social Security Payments When Moving to Italy
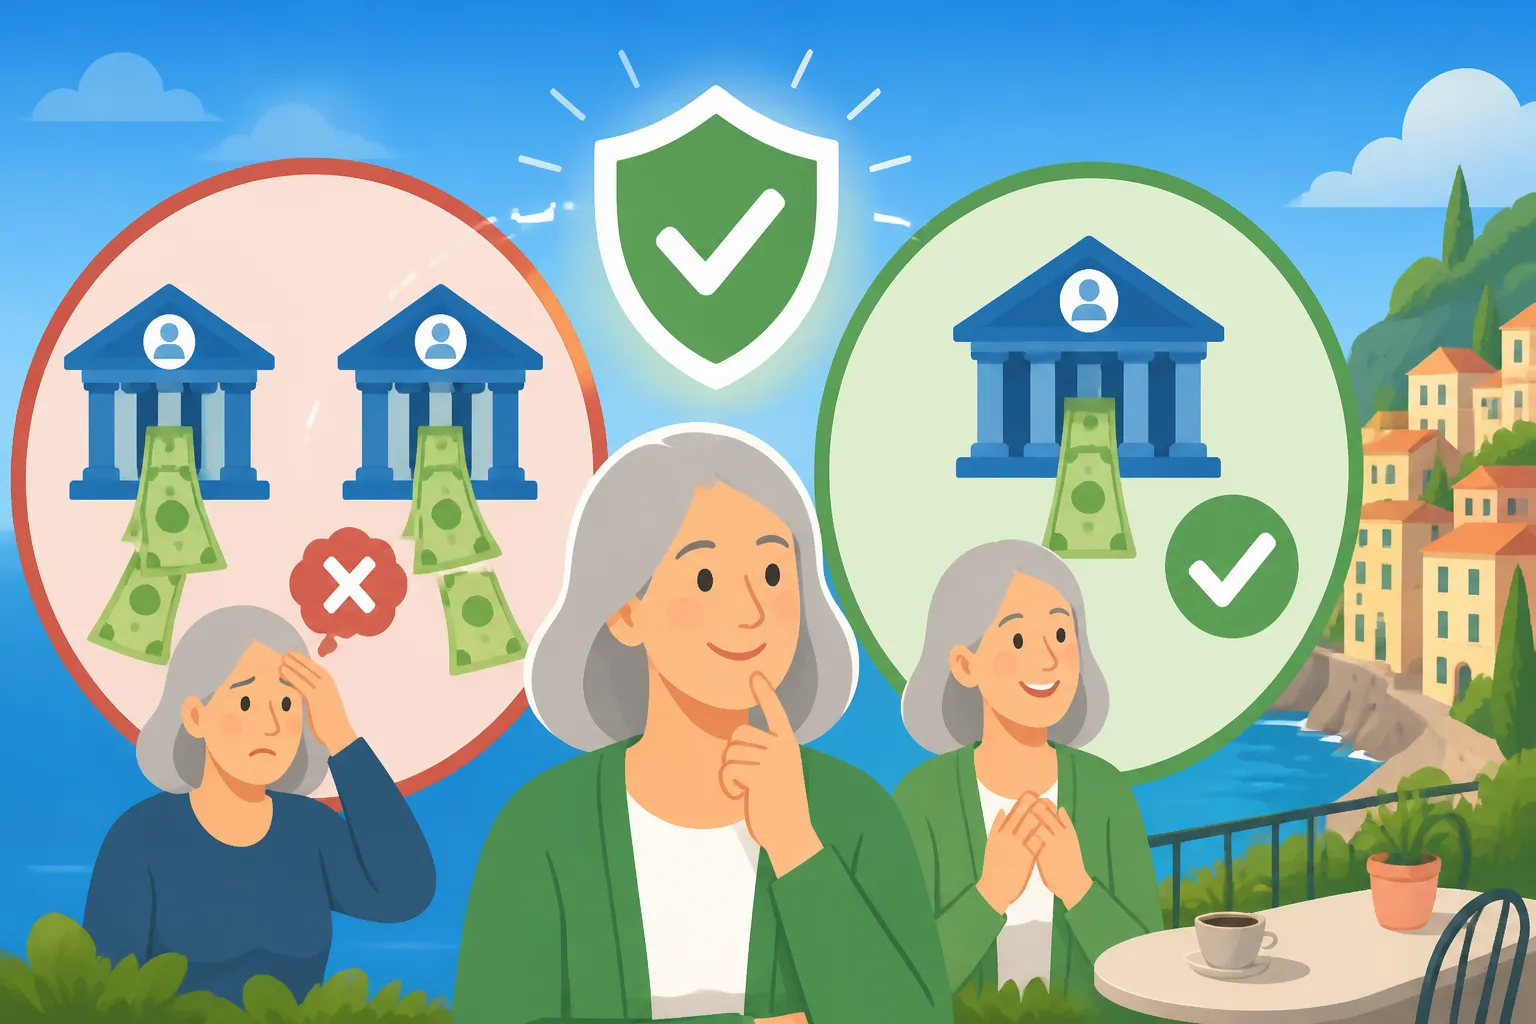
One of the most heart-stopping moments for any new expat in Italy is receiving that first local payslip or seeing a Partita IVA tax bill and realizing how much of your hard-earned cash is disappearing into the Italian social security maw. I remember sitting at a tiny cafe in Trastevere, staring at my laptop in disbelief because I realized I was technically paying into two different national retirement systems simultaneously. This guide will show you exactly how to navigate international agreements so you don't lose thousands to double social security contributions.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
Understanding the Italian Social Security Landscape
Italy’s social security system, managed primarily by the Istituto Nazionale Previdenza Sociale (INPS), is incredibly robust but also notoriously expensive. Unlike some countries where social security is a small line item, in Italy, it covers everything from your future pension and disability insurance to unemployment benefits and even maternity leave. For an employee, these contributions are split between you and your employer, but if you are self-employed, the burden falls almost entirely on your shoulders.
When you first arrive, you might assume that because you are still a citizen of your home country, you should keep paying into your home system to ensure you have a pension back "home." However, once you become a resident and start working on Italian soil, the Italian government generally expects its cut. Without the right paperwork, you could easily find yourself paying 20% to 30% of your income to Italy while your home country’s tax authority continues to demand its own slice for social insurance. This is why understanding The Italian Pension System: How It Works for Expats is the first step in protecting your financial future.
Navigating this requires a deep dive into what we call Totalization Agreements. These are bilateral treaties between Italy and other nations designed to prevent exactly this scenario. They ensure that workers aren't taxed twice for the same income and, more importantly, they allow you to "totalize" or combine your years of work in different countries so you actually qualify for a pension when you retire. Without these agreements, you might work 10 years in the US and 10 years in Italy, yet fail to meet the minimum "vesting" period for either country.
The Power of Totalization Agreements
Italy has signed dozens of these agreements with countries like the United States, Canada, the United Kingdom, and most EU nations. The primary goal of these treaties is to establish which country has the "right" to collect social security taxes based on where the work is physically performed. Generally, the rule is "lex loci laboris"—the law of the place of work. If you are sitting in a home office in Tuscany, Italy considers that work performed in Italy, regardless of where your clients or employer are located.
However, there are major exceptions for "detached workers" or people on short-term assignments. If your home-country company sends you to Italy for a specific period (usually up to 2 or 5 years, depending on the treaty), you can often remain in your home country’s social security system. This is a massive win because it maintains your continuity of benefits back home and usually costs less than the Italian INPS rates. To prove this to the Italian authorities, you need a document known as a Certificate of Coverage.
For Americans, specifically, managing this cross-border complexity is a full-time job. I’ve found that working with specialized firms like Taxes for Expats can be a lifesaver when you’re trying to figure out if your self-employment income qualifies for an exemption under the US-Italy Social Security Agreement. They understand the specific nuances of how the IRS and INPS interact, which is something a local Italian accountant might not fully grasp.
How to Obtain a Certificate of Coverage
The Certificate of Coverage is your "get out of jail free" card when it comes to double payments. If you are being sent to Italy by a foreign employer, they must apply for this certificate from your home country’s social security administration before you move. For example, in the US, the employer applies through the Social Security Administration (SSA). Once issued, this document tells the Italian INPS: "This person is already covered by the US system; do not deduct Italian social security from their pay."
If you are a freelancer or "digital nomad," the process is a bit more "fai-da-te" (do it yourself). You may need to provide proof of your ongoing contributions to your home system. If you are already in Italy and realized you’ve been paying twice, you can sometimes apply retroactively, but it is a bureaucratic nightmare that involves multiple trips to the INPS offices and potentially the Agenzia delle Entrate. It is always better to have this sorted before your residency is finalized at the local Comune.
When dealing with these international applications, you’ll often need to pay small administrative fees or potentially settle voluntary contribution gaps in your home country. I always use Wise for these types of transactions. When you're sending money back to your home country to keep your original pension active, the traditional banks will kill you with hidden exchange rate markups. Using Wise ensures that the exact amount required by your home social security office arrives without being eaten by "intermediary bank" fees.
Comparing Social Security Scenarios for Expats
| Scenario | Primary System | Benefits | Key Document Needed |
|---|---|---|---|
| Short-term Assignment (<2 years) | Home Country | Continuity of home pension | Certificate of Coverage (A1/E101) |
| Long-term Residency (>5 years) | Italy (INPS) | Access to Italian welfare/unemployment | Codice Fiscale: Why It’s Essential for Finance in Italy |
| Self-Employed / Partita IVA | Italy (usually) | High contributions, local healthcare | Registering for Partita IVA (VAT Number) in Italy |
| EU Citizen Moving to Italy | Aggregated EU System | Years count across all EU states | EU Health Card / S1 Form |
Navigating the Partita IVA Trap
If you decide to strike out on your own as a freelancer in Italy, you will likely need to open a Partita IVA. This is where most expats get blindsided by social security. Depending on your profession, you might be enrolled in the Gestione Separata (Separate Management) of INPS. The rates here can hover around 26% of your gross income. If you are also paying voluntary contributions back home or are still being taxed by your home country (as Americans are), your take-home pay can vanish quickly.
The trick to avoiding double payment as a freelancer is to check if your specific profession is covered under the "Self-Employed" section of the totalization agreement. Many agreements state that if you are a resident of Italy, you must pay into the Italian system, which then exempts you from paying the equivalent "Self-Employment Tax" in your home country. This is a crucial distinction. You aren't just trying to avoid paying Italy; you are using your Italian payments to legally "zero out" your social security obligations back home.
This is where your Filing an Italian Tax Return: Step-by-Step Guide becomes vital. You must ensure that your Italian tax return correctly reflects these contributions so that when you file your home country taxes, you can claim the appropriate credits. For US citizens, this involves specific forms that link your INPS payments to your US tax liability. Again, this is where a consultant from Taxes for Expats is worth their weight in gold, as they can help you navigate the "Totalization" vs. "Foreign Tax Credit" debate, which are two very different things.
Common Bureaucratic Hurdles and How to Jump Them
Even with a totalization agreement in place, the Italian bureaucracy is famous for its "left hand not knowing what the right hand is doing" syndrome. You might have your Certificate of Coverage, but the local INPS office might still send you a bill because your residency was registered before the certificate was processed. When this happens, do not ignore the letter. In Italy, a debt to INPS can lead to your bank account being frozen faster than you can say "mamma mia."
You will need to bring your certificate, your How to Get a Codice Fiscale in Italy (and Why You Need One), and a healthy dose of patience to your local INPS office. It often helps to have a "Commercialista" (accountant) who specializes in foreigners. Choosing a Commercialista (Accountant) in Italy isn't just about finding someone to do your math; it's about finding someone who has the direct login credentials to the INPS portal to clear these errors electronically.
While you are getting your paperwork in order, you might need to manage your initial Italian living expenses from a foreign account. I highly recommend that you don't just rely on your home bank card. How to Open a Bank Account in Italy: Requirements and Tips is essential reading, but in the interim, using Wise to hold Euros and pay local bills via bank transfer (Bonifico) will save you a fortune in currency conversion fees while you wait for your first Italian paycheck to clear.
The Long-Term Benefit: Totalizing Your Pension
The most important thing to remember is that paying into the Italian system isn't just a "loss." If you stay in Italy for a significant amount of time, those contributions are being tracked. When you eventually retire, the Italian government will look at your total years of work. If you have 15 years in the UK and 5 years in Italy, the totalization agreement allows Italy to see those 20 years total. They will then pay you a "pro-rata" pension based on the 5 years you spent here, even if the normal minimum to get an Italian pension is 20 years.
This "aggregation of periods" is the hidden gem of international social security law. It means your time in Italy isn't "wasted" from a retirement perspective. However, to make this work, you must keep meticulous records of every INPS payment and every year of "contributi" you've made. You can check your "Estratto Conto Previdenziale" (contribution statement) online through the INPS portal using your SPID (Digital Identity).
For those who are high earners or have complex investment portfolios, the social security conversation often overlaps with broader tax obligations. Understanding Italy's Tax System: A Guide for Foreigners is essential to ensure that your social security strategy doesn't accidentally trigger other tax liabilities. Managing your global wealth while living under the Understanding Italian Income Tax (IRPEF) Brackets Explained requires a holistic approach that looks at both your monthly contributions and your long-term retirement goals.
Important Disclaimer
The information provided in this guide is for educational and informational purposes only. Social security laws and international totalization agreements are subject to frequent change and vary significantly depending on your specific citizenship, residency status, and type of employment. Navigating Italian bureaucracy and international tax treaties is complex and carries significant legal and financial risks. You should always consult with a qualified professional, such as a certified Italian "Commercialista" or a specialized international tax advisor, before making any decisions regarding your social security contributions or tax filings. We are not responsible for any financial losses or legal issues arising from the use of this information.