Pre-Existing Conditions and Italian Visa Insurance: What Gets Excluded
Oh, the joy and the sheer headache of moving to Italy! We all dream of sunny piazzas and endless pasta, but then reality hits you like a high-speed train, especially when it comes to the labyrinthine world of Italian bureaucracy and health insurance. One of the biggest fears I hear from fellow expats, myself included, revolves around those dreaded pre-existing medical conditions. Will they be covered? Will my visa get denied because of them? The anxiety is real, and the answers often feel hidden behind a thick fog of jargon. This guide is here to cut through that fog, offering you a clear, empathetic look at how pre-existing conditions interact with Italian visa insurance requirements and, crucially, what gets excluded, helping you find genuine peace of mind and the right coverage, perhaps with a flexible option like SafetyWing.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
The Harsh Reality of Pre-Existing Conditions and Travel Insurance for Italy
Let's be brutally honest: dealing with pre-existing conditions when moving abroad is tough. It's not just about finding a good doctor or getting your prescriptions refilled; it's about the financial safety net. Many of us have chronic conditions, or perhaps something that flared up years ago but is now stable. The idea that these could prevent you from living your Italian dream, or worse, leave you vulnerable to massive medical bills, is a constant source of stress. It's a worry that often keeps people up at night, pondering whether it's even worth the move.
What Qualifies as a Pre-Existing Condition in Italy's Insurance Context?
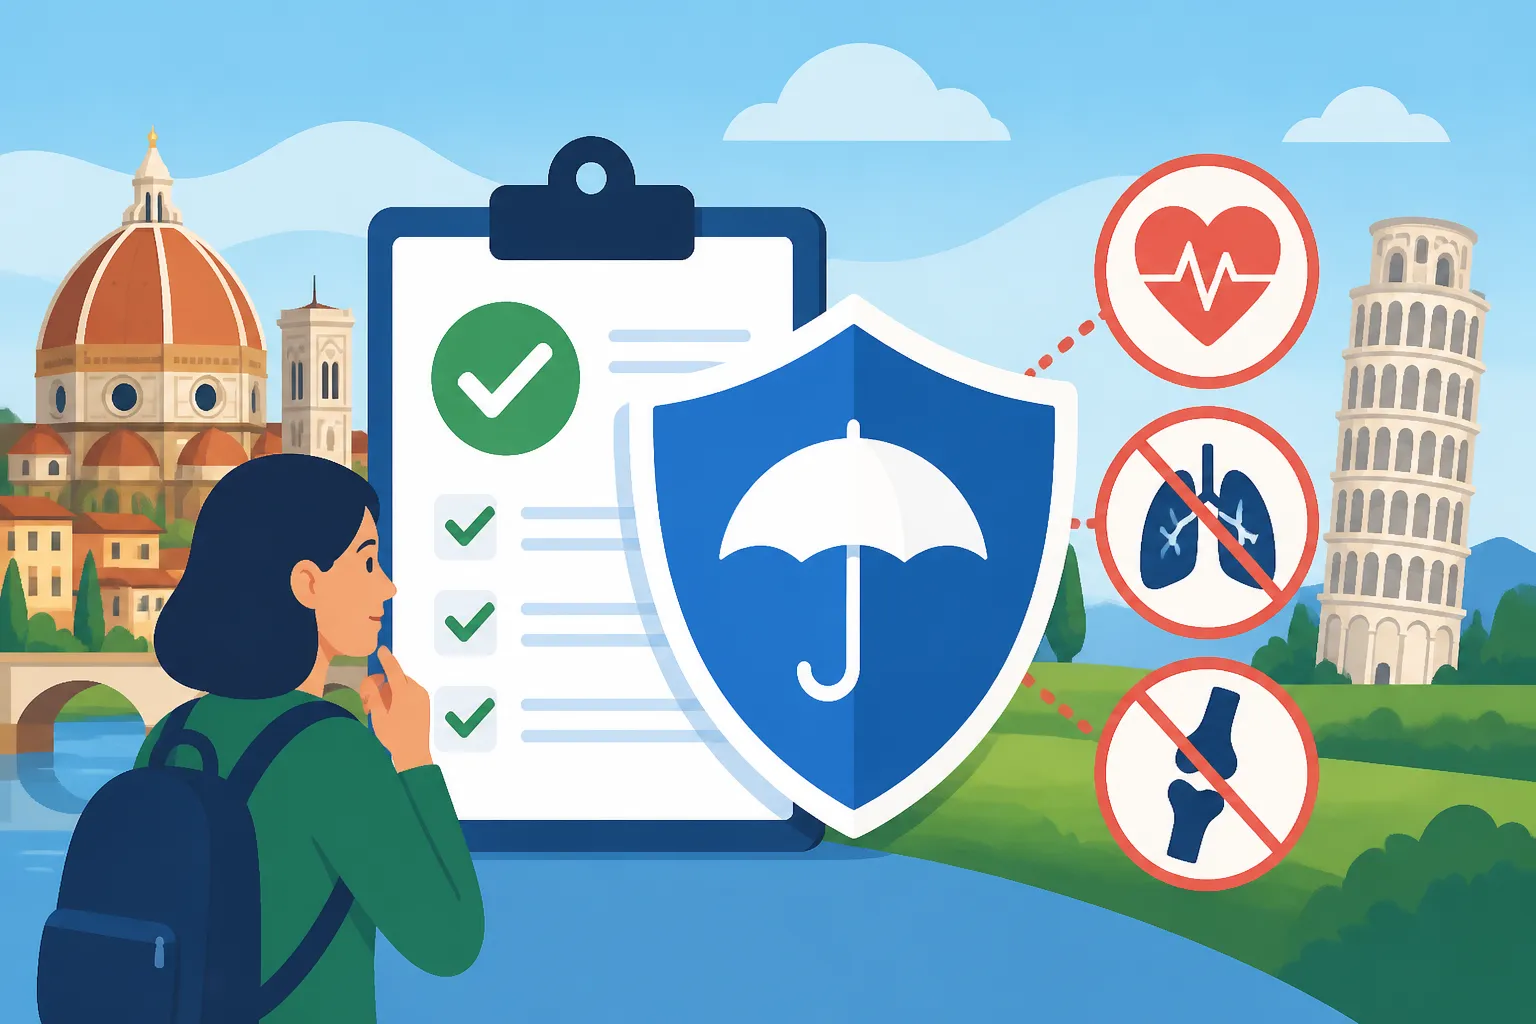
The definition of a "pre-existing condition" isn't always as straightforward as we'd like it to be, and it can vary wildly between insurance providers and even between different types of policies. Generally speaking, an insurance company will consider any illness, injury, or medical condition for which you've received diagnosis, medical advice, care, or treatment (or had symptoms) within a specified period before the effective date of your insurance policy as pre-existing. This period could be anywhere from 6 months to 5 years, depending on the insurer.
For example, if you had a knee surgery two years ago, even if you're fully recovered and have had no issues since, some policies might still flag it as pre-existing. If you manage hypertension with daily medication, or if you've been diagnosed with diabetes, these are almost certainly going to be considered pre-existing. Even something as seemingly innocuous as seasonal allergies that required a doctor's visit last year could technically fall under this umbrella. The key is often whether it's an ongoing condition or one that required medical attention in the recent past. It's not just about current symptoms; it's about your medical history.
Why Standard Travel Insurance Often Falls Short for Expats
Standard travel insurance is designed for short-term trips, for tourists who plan to visit Rome for a week, explore Florence for a few days, and then head back home. It's fantastic for unforeseen accidents or sudden illnesses during your vacation, like a nasty stomach bug from an adventurous street food experience, or a sprained ankle from navigating cobblestone streets.
However, for expats living in Italy, or those planning a long-term stay, standard travel insurance is simply inadequate. These policies typically have strict limitations on pre-existing conditions, often completely excluding coverage for them unless it's a specific, emergency acute onset where the condition suddenly and unexpectedly flares up in a life-threatening way, and even then, usually only to stabilize you. They don't cover routine check-ups, ongoing medication, specialist visits related to your existing condition, or planned treatments. Imagine having a chronic condition that requires regular monitoring; a standard travel insurance policy wouldn't touch that with a ten-foot pole. This gap in coverage is precisely why it's so critical for expats to look beyond basic travel insurance and consider options that understand the unique needs of long-term residents.
Navigating Italian Visa Requirements with Pre-Existing Conditions
Applying for an Italian visa can feel like an Olympic sport, requiring endurance, meticulous preparation, and a thick skin for bureaucracy. The health insurance component is non-negotiable, and if you have a pre-existing condition, it adds another layer of complexity that can make you want to throw your hands up in exasperation.
The Visa Application Headache: Insurance as a Barrier
For many types of Italian visas, especially long-stay visas like the Elective Residence Visa, Student Visa, or the newer Digital Nomad Visa, proof of comprehensive health insurance is a fundamental requirement. The Italian consulates and embassies are very clear: you must demonstrate that you have coverage for medical expenses, hospitalization, and repatriation. The catch? They rarely explicitly state how pre-existing conditions are handled, leaving a huge grey area that causes immense stress for applicants.
I've heard countless stories from friends and fellow expats: people delaying their move, scrambling to find an insurance policy that might be acceptable, or even getting their application stalled because their initial insurance didn't meet the unspoken criteria for pre-existing conditions. It's not uncommon for visa officers, in their assessment, to question the adequacy of a policy if it has blanket exclusions for serious pre-existing conditions, seeing it as insufficient protection for the Italian healthcare system. This makes choosing the right insurance not just a personal health decision, but a critical immigration one. For a deeper dive into the overall process, you can explore the Ultimate Guide to Visas and Immigration in Italy.
Minimum Requirements for Italian Visa Health Insurance
While specific wordings can vary by consulate and visa type, most Italian consulates require health insurance that covers at least:
- Medical Expenses: Coverage for doctor's visits, prescription drugs, and diagnostics.
- Hospitalization: Coverage for inpatient and outpatient hospital care.
- Emergency Care: Coverage for unexpected medical emergencies.
- Repatriation of Remains: In the unfortunate event of death, the cost of returning your remains to your home country.
- Minimum Coverage Amount: Often cited as €30,000, though some advise higher for peace of mind.
- Validity: The policy must be valid for the entire duration of your requested visa or Permesso di Soggiorno, or at least for the first year.
Crucially, the policy usually needs to be valid in the Schengen Area. When it comes to pre-existing conditions, the unspoken expectation is that your insurance should provide meaningful coverage. A policy that completely excludes all pre-existing conditions, even for emergencies, might be deemed insufficient. This is where options like SafetyWing, which offers specific provisions for acute onset of pre-existing conditions, can be particularly appealing for those seeking a more robust solution than typical travel insurance. Understanding the various Health Insurance Requirements for Italian Visa Types: A Comparison can help clarify these often-confusing demands.
Finding the Right Coverage: Options and Exclusions
So, you're not just a tourist. You're moving to Italy, possibly with a pre-existing condition, and you need insurance that satisfies visa requirements and actually protects you. This is where you have to be incredibly discerning, because not all policies are created equal, and exclusions can be hidden in the fine print.
How SafetyWing Addresses Pre-Existing Conditions (and its limitations)
SafetyWing has emerged as a popular choice for digital nomads, remote workers, and expats due to its flexibility and comprehensive travel medical coverage. It's designed for people whose lives are truly international, and it understands the need for continuous, global coverage. One of the key benefits of SafetyWing for those with pre-existing conditions is its provision for acute onset of pre-existing conditions.
What does this mean in plain English? It means that if a pre-existing condition, which was stable and controlled for a certain period (e.g., 60 days) prior to your policy start date, suddenly and unexpectedly flares up to become an emergency and life-threatening condition, SafetyWing may cover the costs for its immediate treatment and stabilization. This is a significant difference from many standard travel insurance policies that offer zero coverage for pre-existing conditions, even in emergencies. For example, if you have well-managed asthma, and you suddenly experience a severe, life-threatening asthma attack in Italy, SafetyWing could cover the emergency room visit and initial treatment.
However, it's vital to understand the limitations. SafetyWing's coverage for pre-existing conditions is generally not for ongoing, routine management. It won't cover your regular doctor's visits for a chronic condition, your ongoing prescription refills, or any planned treatments or diagnostics related to that condition. Its primary purpose in this context is for the acute, unexpected emergency stabilization. For a full understanding of what it entails, especially for a specific visa like the Italy Digital Nomad Visa: Eligibility and Application, it's always best to read their policy document thoroughly and consider contacting their support with specific questions about your condition.
It’s a fantastic solution for flexibility and emergency peace of mind, allowing you to establish residency and then transition to the Italian National Health System (SSN) or more comprehensive private coverage. Remember, while SafetyWing provides excellent travel medical insurance, it's not a substitute for comprehensive expat health insurance if you need ongoing, non-emergency care for your pre-existing conditions. For that, you'll need to explore other options after your initial move, as detailed in Getting Health Insurance in Italy: Public and Private Options.
Comparing Other Options for Comprehensive Coverage
Beyond flexible travel medical insurance, other avenues exist, each with its own pros and cons:
- Expat Health Insurance Providers: These are international private insurance companies specifically designed for people living abroad. Brands like Cigna Global, Aetna International, or Bupa Global often offer plans that can cover pre-existing conditions, sometimes with specific add-ons or riders. The downside? They are typically much more expensive, might require extensive medical underwriting (meaning a thorough review of your medical history), and could impose waiting periods before coverage for pre-existing conditions kicks in. Some might outright decline to cover very serious or unstable conditions. However, if comprehensive, ongoing coverage for a pre-existing condition is a must-have from day one, this is often your best bet, especially if you won't immediately qualify for the SSN.
- Italian National Health System (SSN): Once you've established legal residency in Italy, you can register for the Servizio Sanitario Nazionale (SSN). The SSN provides comprehensive coverage for all registered residents, including pre-existing conditions, often at little to no direct cost (beyond co-pays, known as ticket, for certain services). This is the gold standard for long-term health in Italy. The challenge, of course, is that you usually need your Permesso di Soggiorno and proof of residency before you can enroll. This is why a bridging insurance, like SafetyWing, is so crucial for the initial phase. For more on this, check out How to Register for Italian Healthcare (SSN) as a Foreigner.
- Local Private Italian Insurance: While less common for initial visa requirements, some local Italian private insurers offer plans. These can be trickier for non-Italian speakers to navigate, and their terms for pre-existing conditions might still be restrictive or come with high premiums.
Here's a quick comparison of these insurance types:
| Insurance Type | Pre-Existing Condition Coverage Overview | Best For | Common Exclusions/Limitations |
|---|---|---|---|
| SafetyWing Nomad Insurance | Acute onset of stable pre-existing conditions (emergency only) | Digital nomads, remote workers, bridge coverage for new residents | Not for routine care, planned treatments, or management of stable chronic conditions; specific age/stability requirements |
| International Expat Health Plans | Can be comprehensive, often with riders/add-ons | Expats needing ongoing, non-emergency care for pre-existing conditions | High premiums, potential waiting periods, medical underwriting, some conditions may be declined or have limited coverage |
| Italian National Health System (SSN) | Full, comprehensive coverage for all registered conditions | Legal residents with a Permesso di Soggiorno and registered residency | Not immediately available upon arrival; requires legal residency and SSN registration; bureaucratic process can be slow |
| Standard Travel Insurance | Very limited; usually no coverage for pre-existing conditions | Short-term tourists without chronic conditions | Near-universal exclusion of pre-existing conditions, even for emergencies unless explicitly stated as an "acute onset" (rare) |
Practical Steps and What to Look For
Choosing health insurance when moving to a new country with a pre-existing condition is not a decision to take lightly. It requires diligence, clarity, and a willingness to ask tough questions.
Essential Questions to Ask Before Buying Insurance
Before you click "buy," grab a notebook and make a list of these questions to ask any potential insurer, especially regarding your pre-existing conditions:
- How do you define a pre-existing condition? Get their exact wording and the look-back period.
- Is my specific condition covered? Be explicit. "I have Type 2 diabetes controlled by medication. Is this covered, and for what kind of care?"
- What are the limitations or exclusions for pre-existing conditions? If it's only "acute onset emergency," clarify what that truly means. Does it cover stabilization only, or follow-up care too?
- Are there waiting periods for pre-existing condition coverage? Some policies might cover it, but only after you've been insured for X months.
- What is the maximum payout for pre-existing conditions? Is there a sub-limit that's lower than the overall policy limit?
- Will this policy be accepted for my Italian visa application? While they can't guarantee visa approval, a reputable insurer catering to expats should be familiar with common consulate requirements.
- What is the claims process like, especially for emergencies involving pre-existing conditions? You don't want to be figuring this out in a hospital gown.
- Does the policy cover prescription medications related to my pre-existing condition? This is crucial for ongoing management. You should also understand Bringing Prescription Medications into Italy.
- Does it include repatriation of remains and emergency medical evacuation? These are often mandatory for visas.
Don't be afraid to push for clear answers. Your health and your future in Italy depend on it.
The Importance of Transparency and Documentation
When you apply for insurance, always be transparent about your medical history. Trying to hide a pre-existing condition, even if you think it's minor, can lead to your policy being invalidated when you need it most. Imagine facing a medical crisis, making a claim, and then having it denied because you weren't truthful. That's a nightmare scenario no one wants.
Gather all relevant medical documentation related to your pre-existing conditions. This includes diagnoses, treatment plans, current medication lists, and recent doctor's notes. Having this readily available will not only help you accurately answer insurance application questions but will also be invaluable if you need to make a claim or consult with a new doctor in Italy. Remember that a referral to a specialist doctor in Italy often starts with your family doctor (medico di base), so having your history clear and documented is key.
And once you have your policy, read it. Every single word. Pay particular attention to the sections on "Exclusions," "Definitions," and "Pre-Existing Conditions." Understand your coverage limits, deductibles, and co-pays. Know exactly what you're buying. It's not a fun read, but it's one of the most important documents you'll hold while living abroad. With options like SafetyWing, their policy documents are usually quite clear, so take the time to go through them thoroughly. This diligent preparation will save you countless headaches and potential financial woes down the road, ensuring your journey to Italy is as smooth and stress-free as possible.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute professional medical, legal, or financial advice. While we strive for accuracy, regulations and insurance policies can change. Always consult with a qualified insurance professional, a medical doctor, and the relevant Italian consulate or embassy for personalized advice regarding your specific situation and visa requirements. Remember that insurance coverage for pre-existing conditions can be complex, and policy terms should be carefully reviewed.