How to Insure a Rented Apartment in Italy (Contents Cover)
Imagine coming home to find your apartment flooded because a pipe burst while you were at work, or worse, finding your front door pried open and your high-end electronics missing. I personally spent three weeks in a Roman apartment with a damp ceiling, terrified that my camera gear would be ruined by a neighbor's leak, only to realize my lease didn't protect my belongings at all. This guide breaks down the confusing world of Italian contents insurance so you can protect your assets and your peace of mind.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
The Expat Assumption Trap Why Your Lease Is Not a Safety Net
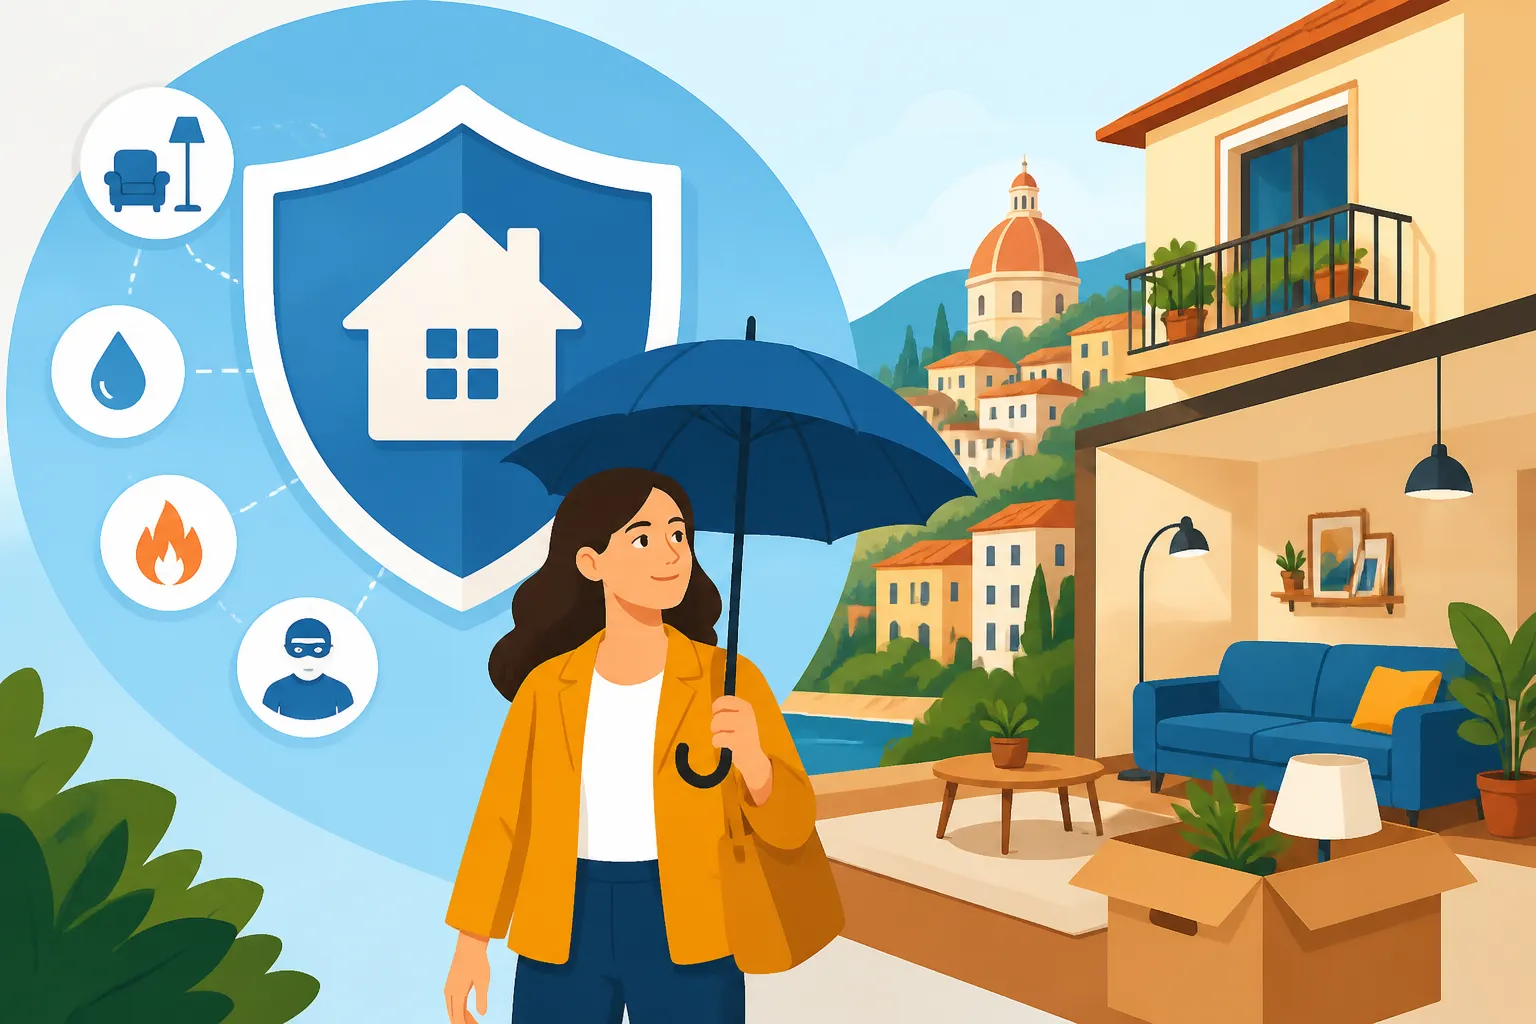
One of the biggest mistakes newcomers make is assuming that the monthly rent check covers everything. In many countries, the landlord’s insurance might offer a modicum of protection for the tenant, but in Italy, the lines are drawn very strictly. Most landlords carry a policy called Assicurazione Fabbricato, which covers the "bones" of the building—the walls, the roof, and the structural integrity. If a fire breaks out and the building burns down, the landlord is covered, but your designer sofa and MacBook are not.
When you are navigating Italian Rental Contracts Explained: 3+2, 4+4, Transitorio, you will often see a clause requiring you to take out your own liability insurance, but they rarely mandate "contents" cover. If you found your place through a platform like Spotahome, you might have felt a sense of security from the professional listing, but even the best rentals require a secondary layer of personal protection. Don't fall into the trap of thinking that because you have a modern flat, your belongings are safe. The reality of Italian plumbing and the lack of high-security communal entrances in older palazzi means the risk is higher than you think.
Understanding Tenant Rights in Italy: Evictions, Deposits, and More is crucial, but remember that these rights rarely extend to the replacement of your personal property. If a pipe bursts—a frequent occurrence in historic city centers—and ruins your wardrobe, the landlord is only responsible for fixing the pipe, not replacing your clothes. This is why a dedicated Assicurazione Contenuto (Contents Insurance) is an absolute necessity for anyone planning a long-term stay.
Structural Insurance vs Personal Property
It is vital to distinguish between what the building owner is responsible for and what falls on your shoulders. The building’s policy covers common areas, the external facade, and damage caused to the building by external factors. However, the moment an incident happens inside your four walls that affects your "moveable" property, you are on your own.
If you are currently Managing Your Budget in Italy: Banking, Currency, and Transfers, you should set aside a small annual fee—usually between €120 and €250—for a comprehensive policy. This is a tiny fraction of the Cost of Living in Italy 2026: Budgeting for Expats, yet it can save you thousands in the event of a burglary or a kitchen fire. Using an eSIM from Airalo while you are first moving in allows you to research these local policies on the go without waiting for your home internet to be installed, which can often take weeks.
The Hidden Clause in Italian Rental Contracts
When you sit down to How to Understand an Italian Rental Contract Clause by Clause, pay close attention to the section on "Danni e Responsabilità." Many Italian landlords will include a phrase that holds the tenant responsible for any damage caused to the apartment through negligence. Without a personal liability and contents policy, you could be held financially responsible for accidental damage to the landlord’s fixtures, such as those beautiful (but expensive) Carrara marble countertops or original parquet floors.
The Three Pillars of Italian Home Insurance
Italian insurance policies for renters are typically "multi-risk" packages. You don't just buy "contents" cover; you usually get a bundle that includes liability, theft, and assistance. This is actually a benefit for expats who are still Registering Residency in Italy (Residenza and Anagrafe) and might not have a local support network yet.
Responsabilità Civile The Oops Insurance
Commonly known as RC Capofamiglia, this is the most important part of any Italian insurance policy. It covers you if you accidentally cause damage to a third party. In a densely populated Italian city, this is a lifesaver. If your washing machine leaks and ruins the 17th-century frescoes on the ceiling of the apartment below you, the costs could be astronomical.
This policy doesn't just cover the apartment, either. In Italy, RC Capofamiglia often follows you outside the house. If you are walking your dog in a piazza and it accidentally trips a passerby, or if you are cycling through a ZTL and clip a parked Vespa, your liability insurance often covers the damages. Given how litigious and bureaucratic things can get, having this protection is as essential as having Healthcare in Italy: An Expats' Guide.
Contents Coverage Furto and Incendio
This is the core of what protects your "stuff." Furto (Theft) and Incendio (Fire) are the two main risks covered here. When calculating your coverage, don't just think about your laptop. Think about your entire life: furniture you’ve bought, kitchen appliances, and even the contents of your fridge. If you’ve spent a fortune on Amazon Italy kitting out your home office or kitchen, you want to ensure those items are scheduled in your policy.
Be aware that Italian policies often have very specific requirements for theft coverage. For example, if you live on the ground floor, the insurer might require you to have inferriate (iron bars) on the windows or a "blindata" (armored) door with a specific European-standard lock. If you don't meet these requirements, they may refuse to pay a claim. If you used Spotahome to find your apartment, check the photos carefully for these security features before signing your lease and buying a policy.
Legal Assistance Tutela Legale
The Italian legal system is notoriously slow and complicated. Many contents insurance policies offer an add-on for Tutela Legale. This provides you with a lawyer paid for by the insurance company to help you resolve disputes with your landlord or neighbors. Whether it's a dispute over the Average Rental Deposit Amount in Italy (2026) or a disagreement about who is responsible for a leaky terrace, having a legal expert in your corner is invaluable for a foreigner who might not yet speak the language of the law.
How to Choose the Right Policy and Provider
Selecting an insurer in Italy can feel like a daunting task, especially with the language barrier. You will find big names like Generali, Allianz, and UnipolSai, but there are also newer digital players like Prima or Conte.it that offer streamlined English-language interfaces.
Documentation You Can Not Live Without
To get insured, you will need your Codice Fiscale (Tax Code) and a copy of your registered rental contract. The insurer will ask for the square footage of the apartment and the "vivaio" or value of the contents you wish to insure. It is always better to slightly over-insure than to under-insure. Italy uses a principle called "pro-rata," meaning if you insure your belongings for 50% of their actual value, the company will only pay 50% of any claim, regardless of the size.
| Coverage Type | What it Covers | Estimated Annual Cost | Recommended For |
|---|---|---|---|
| RC Capofamiglia | Third-party liability (flooding a neighbor, etc.) | €50 – €80 | Everyone |
| Contents (Basic) | Fire, smoke, and water damage to your items | €70 – €120 | Budget-conscious students |
| Theft (Furto) | Burglary and robbery (often including outside the home) | €40 – €100 | People with high-end tech/jewelry |
| Legal Protection | Lawyer fees for housing disputes | €30 – €50 | Long-term residents |
Online Platforms vs Traditional Agencies
Digital insurers are great for quick quotes and often have better apps for Managing Your Budget in Italy: Banking, Currency, and Transfers. However, traditional agencies (where you walk into an office and sit with an agent) can offer a more tailored experience. If your apartment has unique features—like an antique fireplace or a shared courtyard—a local agent might understand the specific risks better.
While you are waiting for your permanent residence to be finalized, you can use Airalo to keep your data active as you visit different agencies. Many traditional agents do not speak fluent English, so having a translation app ready on your phone is a must. If you’ve recently kitted out your apartment with smart home gadgets from Amazon Italy, make sure to mention these, as they can sometimes lower your premium by proving you have better security monitoring.
When Disaster Strikes The Claims Process Step-by-Step
Filing a claim in Italy requires a meticulous approach. The term for a claim is sinistro, and you usually have a very short window—often only 48 to 72 hours—to notify your insurer.
Getting the Denuncia Right
If you have been robbed, your first stop is the Carabinieri or the Polizia di Stato to file a Denuncia (official report). You cannot file an insurance claim for theft without this piece of paper. Be prepared to list every item that was taken, including serial numbers if you have them. This is why keeping digital receipts from places like Amazon Italy is so helpful; you can quickly pull up exactly what you paid for that missing tablet or air fryer.
Check How to Spot Rental Scams in Italy Before Paying a Deposit before you ever move in, as a secure, legitimate rental is much easier to insure. Once you have your denuncia, you must send it to your insurance company via PEC (Certified Email) or a registered letter (Raccomandata A/R). In Italy, a standard email is often not considered legally binding for claims.
Documenting Everything for the Perito
After you report the claim, the insurance company will likely send a perito (adjuster) to your home. This person’s job is to verify the damage and estimate the cost. Do not throw anything away before they arrive. If a pipe burst and ruined your rug, keep the soggy rug. Take high-quality photos and videos of everything immediately after the incident occurs.
If the damage requires immediate repairs—for instance, a broken window that needs boarding up—you can often call the insurance company's emergency 24-hour hotline. They can send How to Find Reliable Tradespeople for Home Repairs in Italy who are already vetted by the company. This can save you the headache of finding a plumber on a Sunday in August when the whole country is on holiday.
Specific Expatriate Considerations
As an expat, your needs might differ from those of a local. You may have expensive international relocation items, specialized work equipment, or expensive sporting gear.
- Global Coverage: Some Italian contents policies offer "Away from Home" coverage. This means if your phone is snatched while you are sitting at a cafe in Milan, the policy covers it.
- Valuable Collections: If you have jewelry or art worth more than a few thousand euros, you will need a "Stima Accettata" or an appraisal. Standard contents policies usually have a "per-item" limit.
- Natural Disasters: Depending on where you live (like the hills of Tuscany or the seismic zones of Umbria), check if earthquake or flood coverage is included. These are often separate add-ons in Italy.
If you are staying in a flat you found on Spotahome and plan to move after a year, check the "Disdetta" (cancellation) policy of your insurance. Most Italian policies automatically renew unless you send a cancellation notice at least 30 to 60 days in advance.
Final Thoughts on Staying Protected
Insuring your rented apartment in Italy is about more than just protecting your laptop; it’s about insulating yourself from the unpredictable nature of Italian bureaucracy and old-world infrastructure. By taking out a comprehensive contents and liability policy, you ensure that a single accident doesn't derail your Italian dream. Whether you are buying new gear on Amazon Italy or exploring your new neighborhood with data from Airalo, knowing your home is secure allows you to truly enjoy the dolce vita.
Disclaimer
This guide is for informational purposes only and does not constitute legal or financial advice. Insurance regulations and policy terms in Italy can change frequently. Always consult with a licensed insurance professional or a qualified legal advisor before signing any contracts or making financial commitments regarding home insurance.